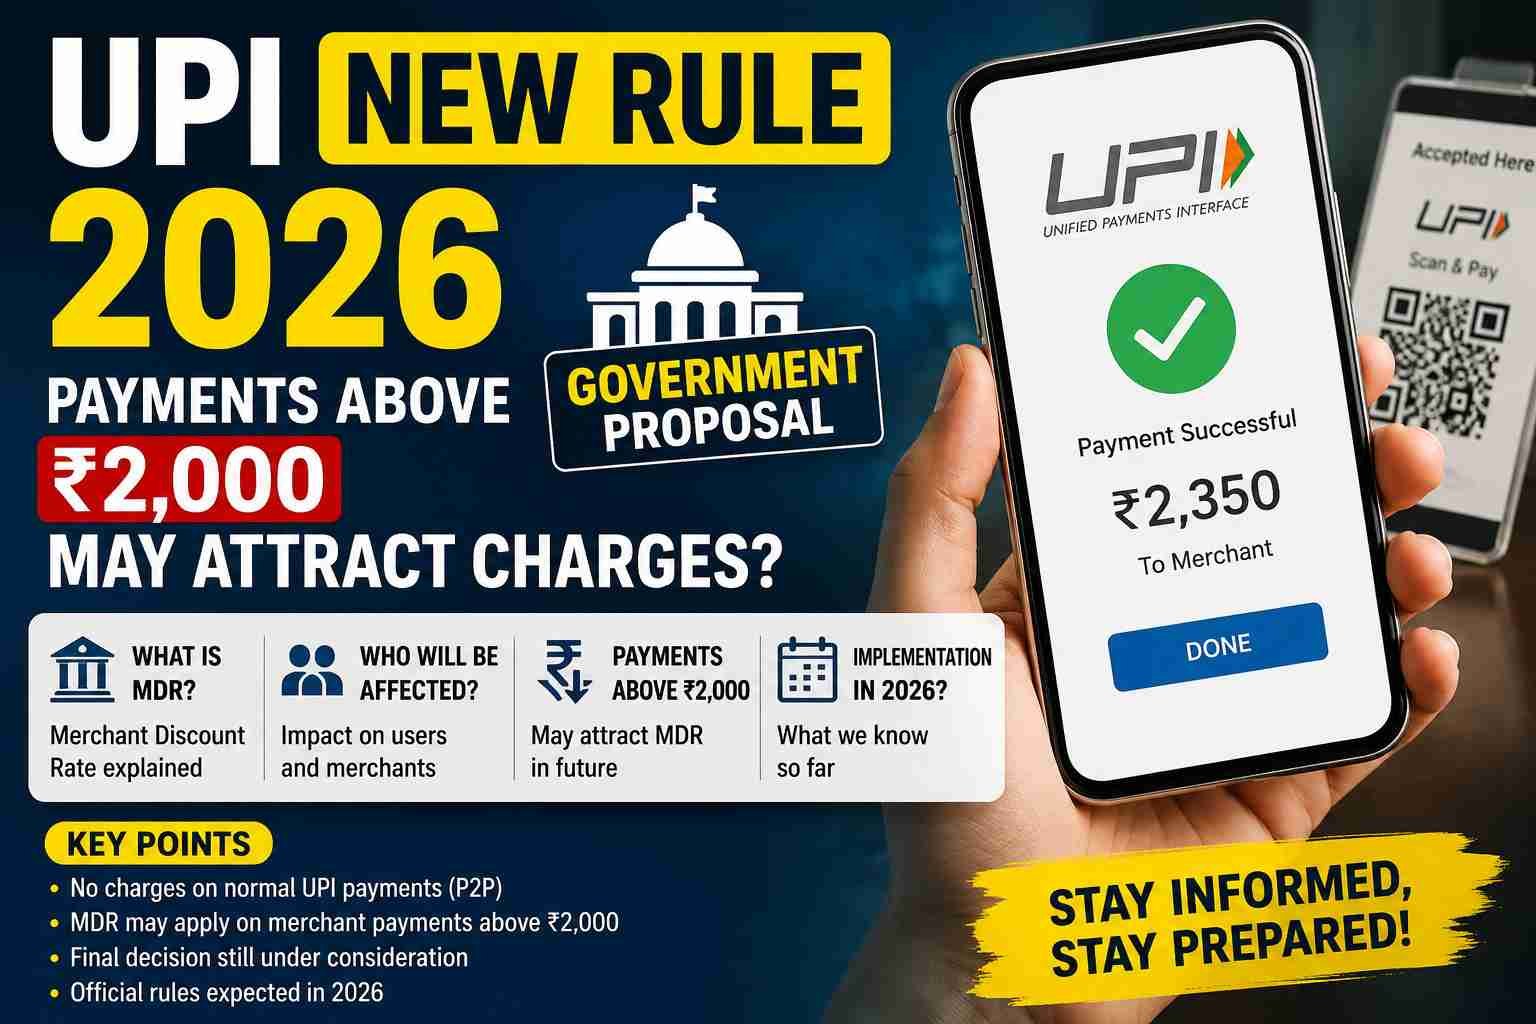

From October 15, 2026, selected UPI merchant payments above ₹2,000 will come under a new Merchant Discount Rate (MDR) framework. The standard MDR is 0.4%, subject to a ₹300 cap, while certain sectors have concessional rates. Here is how users and merchants can understand and check the applicable UPI charges.
UPI Charges From October 15: What Is Changing
UPI charges are changing for selected merchant transactions from October 15, 2026. Under the revised framework announced by the National Payments Corporation of India (NPCI), a 0.4% MDR will apply to specified Person-to-Merchant, or P2M, UPI transactions above ₹2,000. The MDR will be capped at ₹300 for a single transaction.
This does not mean that every UPI payment will suddenly attract a fee.
The Ministry of Finance has clarified that person-to-person UPI payments will remain free regardless of the amount transferred. Merchant payments up to ₹2,000 will also remain free, along with transactions covered under the zero-MDR framework for eligible small merchants. The government says around 96% of P2M transactions will remain unaffected.
For consumers, the most important distinction is between the payment amount and the MDR. The MDR is a payment-processing charge within the merchant-side ecosystem and is not supposed to be added to the customer’s UPI bill.
How to Check Whether a UPI Payment Attracts MDR
The easiest way to understand whether a transaction falls under the new framework is to check four things: who is receiving the money, how much is being paid, the merchant category and whether the transaction is covered by an exemption or concessional rate.
First, check whether the payment is being made to a merchant. A transfer to a friend, family member or another individual is a P2P transaction and remains outside the new MDR framework.
Next, check the transaction value. A standard eligible merchant payment of ₹2,000 or less will remain free. If the payment is above ₹2,000, the merchant category and applicable MDR need to be considered.
Consumers should also check the payment confirmation screen and final transaction receipt generated by their UPI app or merchant. If a merchant attempts to add a separate UPI fee to the customer’s bill, the customer should ask for a clear explanation because the new MDR is intended to be borne within the merchant payment ecosystem.
How Much Is the New UPI MDR?
For eligible merchant transactions above ₹2,000, the standard MDR is 0.4%.
The calculation is straightforward.
For a ₹3,000 eligible merchant payment, 0.4% works out to ₹12.
For a ₹5,000 payment, the MDR would be ₹20.
For a ₹10,000 payment, it would be ₹40.
At ₹75,000, the 0.4% calculation reaches ₹300. For transactions above ₹75,000, the MDR remains capped at ₹300 per transaction.
However, these calculations describe the merchant-side MDR. They should not be interpreted as an additional amount that consumers must automatically pay on top of their purchase.
The government has also said that MDR is not a tax collected by the government or NPCI. Instead, it is distributed among participants in the payments ecosystem, including banks and payment application providers.
Special UPI Charges for Fuel, Railways and Other Services
Not every eligible payment will use the standard 0.4% rate.
Certain categories have been assigned concessional rates. Reports based on the revised framework indicate that selected services, including railways, telecom, fuel, insurance and utility payments, can attract a flat ₹5 MDR on transactions above ₹2,000.
This distinction is important when checking a transaction.
For example, applying 0.4% automatically to every payment above ₹2,000 could produce the wrong figure. The merchant’s category determines which MDR structure applies.
Capital-market transactions also have a separate concessional rate. Reports on the framework state that certain capital-market payments, including mutual fund and securities-related transactions, will attract a lower 0.02% MDR, subject to the applicable cap.
Users therefore need to look at the type of transaction rather than relying only on the payment amount.
Will Customers Have to Pay the UPI Charge?
The government has stated that customers should not bear the new MDR directly.
The Ministry of Finance has advised banks to ensure that merchants do not pass the newly introduced UPI MDR on to customers. The government is also examining ways to monitor whether merchants attempt to recover the fee from consumers.
This means customers should be cautious if a shop, restaurant, online seller or service provider suddenly adds a separate UPI surcharge to a bill.
A merchant may have its own pricing policies, but the newly announced MDR itself is a merchant-side payment-processing charge. The government has specifically sought to prevent it from being passed on to consumers.
For everyday users in Tier-2 and Tier-3 cities, this distinction matters because UPI QR payments are widely used at grocery stores, restaurants, pharmacies, local service businesses and other small establishments.
How Merchants Can Check Their UPI Charges
Merchants should not rely solely on the amount displayed in the customer’s UPI app.
The actual MDR is linked to the merchant’s payment arrangement and transaction classification. Businesses should check their acquiring bank, payment aggregator or UPI service provider’s settlement statement after the new framework comes into effect.
The settlement report should help merchants identify the transaction amount, applicable MDR and any relevant tax treatment.
An additional 18% GST is expected to apply to the MDR charged on eligible UPI transactions. GST-registered businesses may be able to claim the applicable amount as input tax credit, subject to the usual tax rules. Importantly, the GST applies to the MDR, not to the entire value of the customer’s purchase.
For example, if the MDR on an eligible ₹10,000 transaction is ₹40, the reported GST would apply to that ₹40 MDR rather than the entire ₹10,000 transaction value.
What Small Merchants Should Know About UPI MDR
The new framework includes protections for eligible small merchants.
The government has said that transactions covered under the zero-MDR framework for small merchants will remain free. Reports indicate that small merchants receiving up to ₹1 lakh per month through eligible UPI QR collections can remain outside the new MDR levy, subject to the applicable framework and conditions.
This is particularly relevant for small retailers, neighbourhood stores, local food businesses and service providers in smaller Indian cities.
Merchants should therefore check their monthly UPI collection levels and confirm their classification with their acquiring bank or payment provider rather than assuming that every transaction above ₹2,000 will automatically attract the standard 0.4% MDR.
What UPI Users Should Check Before October 15
Consumers do not need to stop using UPI because of the new framework.
Instead, users should understand the difference between P2P transfers and merchant payments. They should also check the final amount before approving a payment and retain the digital receipt for higher-value purchases.
If a merchant adds a separate UPI fee, customers can ask why the amount has been added and request an itemised bill.
The new framework does not remove free UPI payments for everyday users. Person-to-person transfers remain free, and merchant transactions up to ₹2,000 remain free. The government has also said that approximately 96% of P2M transactions will remain unaffected.
As October 15 approaches, banks, payment apps, aggregators and merchants are expected to update their systems for the new framework. Users should therefore rely on the latest transaction receipt and official information from their payment provider when checking a particular charge.
Key Takeaways
- From October 15, 2026, a 0.4% MDR will apply to specified UPI merchant transactions above ₹2,000, subject to a ₹300 cap.
- Person-to-person UPI transfers and merchant payments up to ₹2,000 remain free under the announced framework.
- Certain sectors such as railways, fuel, telecom, insurance and utilities have concessional or flat-rate structures.
- The MDR is intended to be borne within the merchant payment ecosystem and should not be directly passed on to consumers.
FAQ
When will the new UPI MDR start?
The revised UPI Merchant Discount Rate framework is scheduled to take effect from October 15, 2026.
Will I be charged for sending money to friends through UPI?
No. Person-to-person UPI transactions will continue to remain free, regardless of the amount transferred.
How much is the standard UPI MDR for merchant payments above ₹2,000?
The standard MDR is 0.4% for specified eligible merchant transactions above ₹2,000, with the charge capped at ₹300 per transaction.
Can a shopkeeper add the UPI MDR to my bill?
The government has directed the payment ecosystem to ensure that the MDR is not passed on directly to consumers. If a merchant adds a separate UPI surcharge, customers can ask for an itemised explanation and check the applicable rules.
(Internal keywords: UPI charges October 2026, UPI MDR October 15, UPI merchant charges, UPI 0.4 percent MDR, UPI charges above ₹2000, UPI payment charges India, UPI MDR explained, UPI merchant payment rules, UPI charges for consumers, how UPI MDR works)